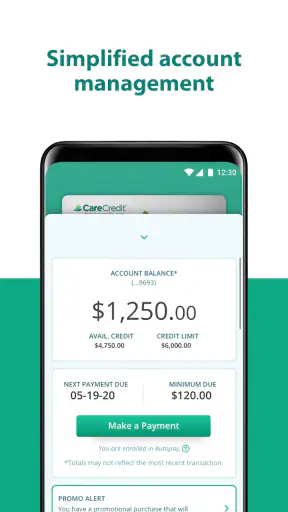
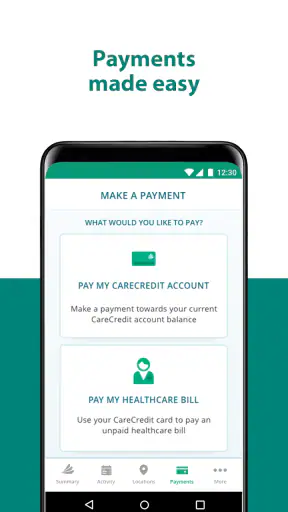
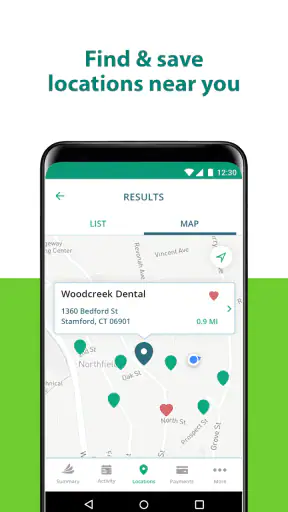
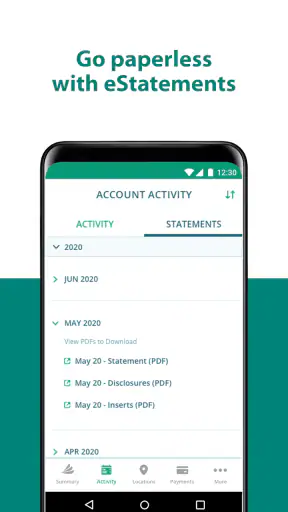
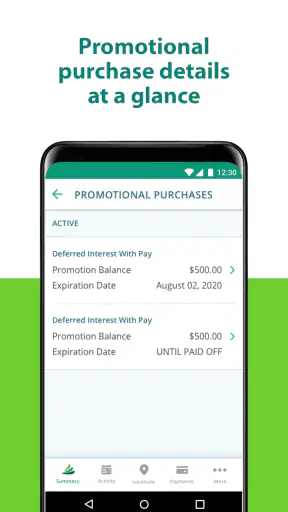
Managing a healthcare financing account is usually not something I want to turn into a long desktop task. That is where CareCredit Mobile makes sense. This free finance app from Synchrony is built around the practical jobs CareCredit users are most likely to need: checking an account, making a payment, and using a digital card when paying for eligible care. After spending time with it, my view is straightforward: it is most useful as a focused account-management tool, not as a general budgeting app or a replacement for a full banking application.
The app has been available since October 27, 2015, and its current version is 6.5.1. It is rated for Everyone and requires Android 11 or later. Its 4.2 average from around 45 thousand ratings, together with more than a million installs, suggests that many people find the basic workflow dependable enough for recurring account tasks. I would still judge it by a more personal question: does it reduce the effort of handling your CareCredit account compared with signing in through a browser, calling support, or keeping the account out of sight until a statement arrives?
What I would consider before choosing it
Start with the job you actually need to complete
CareCredit Mobile is easiest to evaluate when I separate healthcare financing from ordinary money management. If I need to see my CareCredit account, make a payment, or bring up a digital card, the app has a clear purpose. If I want one place to track groceries, rent, savings, credit cards from several issuers, and a monthly spending plan, this is the wrong category of tool.
That distinction matters because a specialized app can feel either refreshingly simple or frustratingly narrow. I prefer the narrowness here when I already have a CareCredit account and want a direct route to it. I do not expect it to replace my bank’s app, a debt planner, or a personal finance dashboard. The best decision depends less on how many features appear on a screen and more on whether the app covers the one account that needs attention.
Think about speed, confidence, and the moment of payment
For me, the important test is not whether an app looks polished during a casual browse. It is whether I can open it before or after a healthcare visit and quickly confirm what I need. A payment task has a different emotional weight from checking a restaurant transaction. I want the account context to be clear, the action to feel deliberate, and the result to be easy to verify afterward.
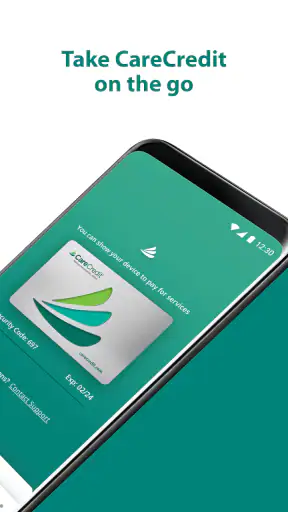
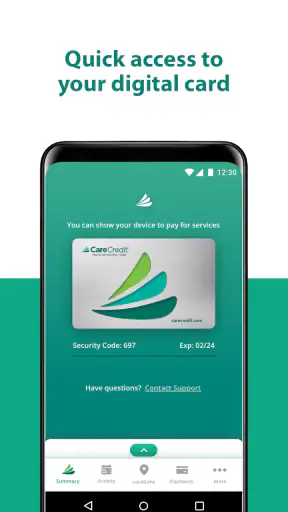
The digital card is another practical consideration. A physical card can be left at home, misplaced, or buried in a wallet. Having access to a digital version can make the app more useful at the point of care. I would not treat that convenience as a reason to ignore the details of the account, though. Before using any financing option, I would still review the terms presented for the purchase and make sure the payment plan fits my budget.
Check the device requirement before committing
The Android requirement is worth checking early. A phone running an older operating system may not be suitable, even if it handles other finance apps without trouble. That is a small detail, but it can become a major annoyance when someone needs account access before an appointment. I would verify the phone’s software first rather than discovering the limitation during an urgent payment task.
The Everyone content rating also makes the app broadly approachable from a store-rating perspective. That does not mean every financial decision inside it is simple. The app may make account access more convenient, but the responsibility for understanding balances, payment timing, and financing terms remains with the account holder.
My practical test for a finance app like this
I look for four things: whether the app gets me to the right account without unnecessary detours, whether the payment flow encourages careful review, whether the digital card is useful in a real situation, and whether it gives me enough confidence to confirm that an action succeeded. I also consider what happens when the app is not enough. A specialized mobile account tool should complement statements, account correspondence, and customer support rather than pretending every question can be solved from one screen.
That last point is important for CareCredit Mobile. I would use it for routine control and quick access. For complicated disputes, unclear transactions, or questions about a healthcare provider’s financing offer, I would slow down and use the appropriate official support route instead of repeatedly tapping through the app.
Where CareCredit Mobile wins in everyday use
The clearest strength is focus. The app is designed around a CareCredit relationship, so I do not have to search through unrelated banking products to reach the relevant account. That makes it more direct than a general financial dashboard when my immediate task is a CareCredit payment or digital-card check.
I also like the difference between “I should deal with this later” and “I can handle this now.” A browser login can be perfectly adequate, but mobile access is more natural when I am away from a desk. If I receive a reminder while commuting, sit in a clinic waiting room, or remember a payment while preparing for bed, a dedicated app can turn that thought into a completed task before it disappears.
The app’s focused design is especially helpful for people who use CareCredit occasionally rather than every day. Infrequent users may not remember where they stored a login bookmark or which page contains the payment action. A recognizable app icon and a purpose-built account path can reduce that friction. I would still keep my login details secure and avoid treating a phone as the only place where important financial information exists.
A realistic scenario: handling the account after a healthcare visit
Imagine that I have just paid for an eligible service and want to make sure I can manage the resulting account responsibly. Instead of waiting until the next statement, I can open CareCredit Mobile, review the account, and decide what action makes sense. If I need to make a payment, the app puts that task in the same place where I can access the account. If I need the digital card for a future transaction, I know where to look rather than searching through email or a wallet.
The value here is not dramatic automation. It is the reduction of small delays that often cause financial tasks to be forgotten. I find that useful because healthcare expenses can already involve appointments, receipts, insurance questions, and follow-up care. A dedicated account app cannot simplify all of that, but it can make one part less scattered.
One useful workflow: use the app as a confirmation habit
A habit I would recommend is separating the payment action from the confirmation check. I would open the account, review the destination and amount carefully, submit the payment, and then return to the account view to confirm that the app reflects the action as expected. I would also retain any confirmation information presented during the process rather than assuming that closing the app means everything completed.
This is a non-obvious advantage of having a mobile account tool: it can support a repeatable routine. The app is not merely a place to tap “pay.” It can become the checkpoint I use before and after a payment. That is particularly valuable when I am distracted, handling several bills, or paying from a phone in a busy environment.
The digital card is convenient, but convenience needs boundaries
Access to a digital card is one of the more practical reasons to keep the app installed. A digital card can be easier to retrieve than a physical one when I am arranging care or need the account details available during a transaction. It also reduces dependence on carrying an extra card everywhere.
My caution is that digital access should not encourage rushed borrowing. Having the card immediately available makes a transaction easier, but it does not make the financing cost-free or automatically suitable. I would treat the digital card as an access feature, not as a spending signal. Before agreeing to a purchase, I would ask what I will owe, when payments are due, and whether the arrangement works alongside my other commitments.
Where the app may feel limited
The same specialization that makes CareCredit Mobile convenient can make it feel incomplete if I expect broader financial tools. Someone looking for spending categories, savings goals, bill aggregation, or a combined view of several lenders will probably need another app. I would not install this expecting it to explain my entire financial position.
There is also a difference between account access and account understanding. A mobile interface can show me the account and help me act, but it cannot make a financing decision wise by itself. I still need to read the terms associated with a purchase and consider whether I can maintain the required payment schedule. This is a limitation of scope rather than a flaw unique to the app, but it affects the decision to use it.
Another possible friction point is the Android requirement. If my phone cannot run Android 11 or later, the app is not a practical solution on that device. I would not change phones solely for a single account-management app unless the account was important enough to justify that expense. In that situation, a browser-based route or another official access method may be the more sensible alternative.
How it compares with the usual alternatives
The most obvious alternative is using a mobile browser. A browser can be better when I do not want another installed app, when I use several devices, or when my phone does not meet the app’s operating-system requirement. It may also suit someone who accesses the account only a few times a year. The trade-off is that the browser route can feel less immediate, especially when I need the digital card or want a familiar one-tap entry point.
A general banking app is better for people who want a complete view of everyday money. If I am comparing my checking balance, credit-card payments, and savings goals in one place, my bank’s app or a broader personal finance service may be more useful. Those tools, however, are not automatically a substitute for a dedicated CareCredit account experience. They may show a payment leaving a bank account without giving me the same direct relationship with the CareCredit account itself.
A paper statement or phone call may still be preferable in specific cases. Someone who is uncomfortable managing financial accounts on a smartphone may value a non-app process more. Likewise, an account problem that requires explanation is not necessarily improved by a mobile interface. I see CareCredit Mobile as the fastest option for routine actions, not the universal answer for every account question.
Who should use it, and who should skip it?
I would recommend it to an existing CareCredit user who wants convenient mobile access, expects to make payments from a phone, or values having a digital card available. It is also a reasonable choice for someone who tends to postpone account tasks until they are back at a computer. The free price makes trying it low-risk in financial terms, although the account itself still involves real borrowing decisions.
I would be more cautious about recommending it to someone who wants a complete household finance system. If the main goal is debt payoff planning across multiple accounts, this app will not be the center of that workflow. I would also point occasional users toward whichever access method they find easiest and safest, especially if installing a dedicated app feels unnecessary.
The cost of switching to a dedicated mobile workflow
Switching from browser access to an app is not financially expensive because the app is free, but there is still a small practical cost. I need to install it, sign in, become familiar with its layout, and decide how it fits into my existing payment routine. I would not delete old records or stop checking statements simply because the app is now my preferred access point.
The bigger switching cost is behavioral. Once an app makes payments easy, I might be tempted to act quickly without reviewing the account carefully. My solution would be to keep a simple routine: check the account context, review the amount, complete the action, and verify the result. That makes the convenience work for me rather than turning speed into carelessness.
There is also a device-continuity question. If I replace my phone, lose access to it, or use another device while traveling, I need a backup way to manage the account. I would keep important account information organized securely and avoid relying on the app as my only record. A dedicated app is a useful door into the account, but I still want another route when the phone is unavailable.
My recommendation after weighing the trade-offs
CareCredit Mobile earns my recommendation for a specific audience: people who already use CareCredit and want a straightforward mobile way to manage that account. Its strongest qualities are focus, convenience, payment access, and the ability to use a digital card. The 4.2 average rating and broad adoption indicate that it has become a familiar option for many account holders, while Synchrony gives the app a clear connection to the service it represents.
I would not recommend it as a substitute for a budgeting app, a bank app, or careful reading of financing terms. Its value is narrower and more practical. When I need to check the account, make a payment, or access the digital card, that narrow purpose is exactly why I would choose it over a general finance tool.
If your phone runs Android 11 or later and you want routine CareCredit tasks available without opening a browser, I think installing it is sensible. Use it as a controlled account-management shortcut, confirm payments instead of assuming they went through, and keep broader financial planning somewhere else. For that use case, the best reason to choose CareCredit Mobile is not that it does everything, but that it keeps one important healthcare-financing account close at hand without pretending to be your entire financial life.


